Looking ahead
Changes to risk management and regulatory reporting brought about by regulatory change is proceeding at a rapid pace and on an unprecedented scale. Keeping up with the changing regulatory requirements imposes a high degree of complexity and a key challenge for small- and medium-sized banks. Katalysys can be your partner in managing this change. We can assist the bank’s risk management and regulatory reporting functions to stay ahead with these changes.
Basel 3.1
On 7 October 2026, the Prudential Regulation Authority (PRA) published Consultation Paper CP13/26 – Updating regulatory thresholds: An autopilot approach, setting out a proposed framework to minimise “prudential drag” by automatically indexing 128 regulatory thresholds across the PRA Rulebook and PRA guidance in line with UK nominal GDP. Responses to both the consultation and the associated discussion paper are due by 7 February 2027.
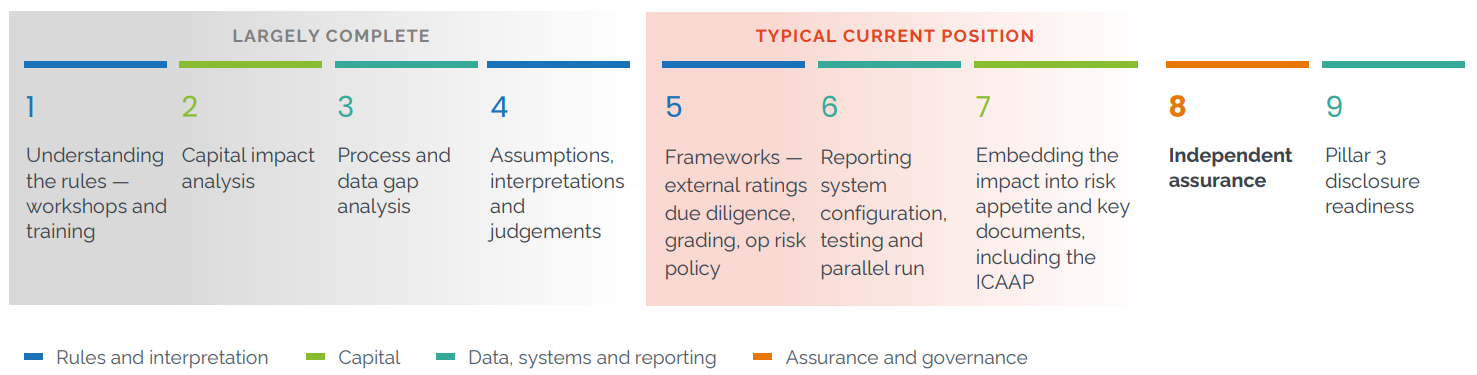
Most firms have moved beyond impact assessment. The hard work now is documenting judgements, configuring reporting, running credible parallel calculations and securing board confidence before 1 January 2027.
On 19 February 2026, the Prudential Regulation Authority (PRA) published Consultation Paper CP3/26, setting out proposed amendments to the PRA Rulebook to reflect the implementation of HM Treasury's (HMT) Overseas Prudential Requirements Regime (OPRR). Following consultation, the PRA published Policy Statement PS16/26 on 14 July 2026, confirming its final rules.
Regulatory updates
On 7 October 2026, the Prudential Regulation Authority (PRA) published Consultation Paper CP13/26 – Updating regulatory thresholds: An autopilot approach, setting out a proposed framework to minimise “prudential drag” by automatically indexing 128 regulatory thresholds across the PRA Rulebook and PRA guidance in line with UK nominal GDP. Responses to both the consultation and the associated discussion paper are due by 7 February 2027.
Most firms have moved beyond impact assessment. The hard work now is documenting judgements, configuring reporting, running credible parallel calculations and securing board confidence before 1 January 2027.
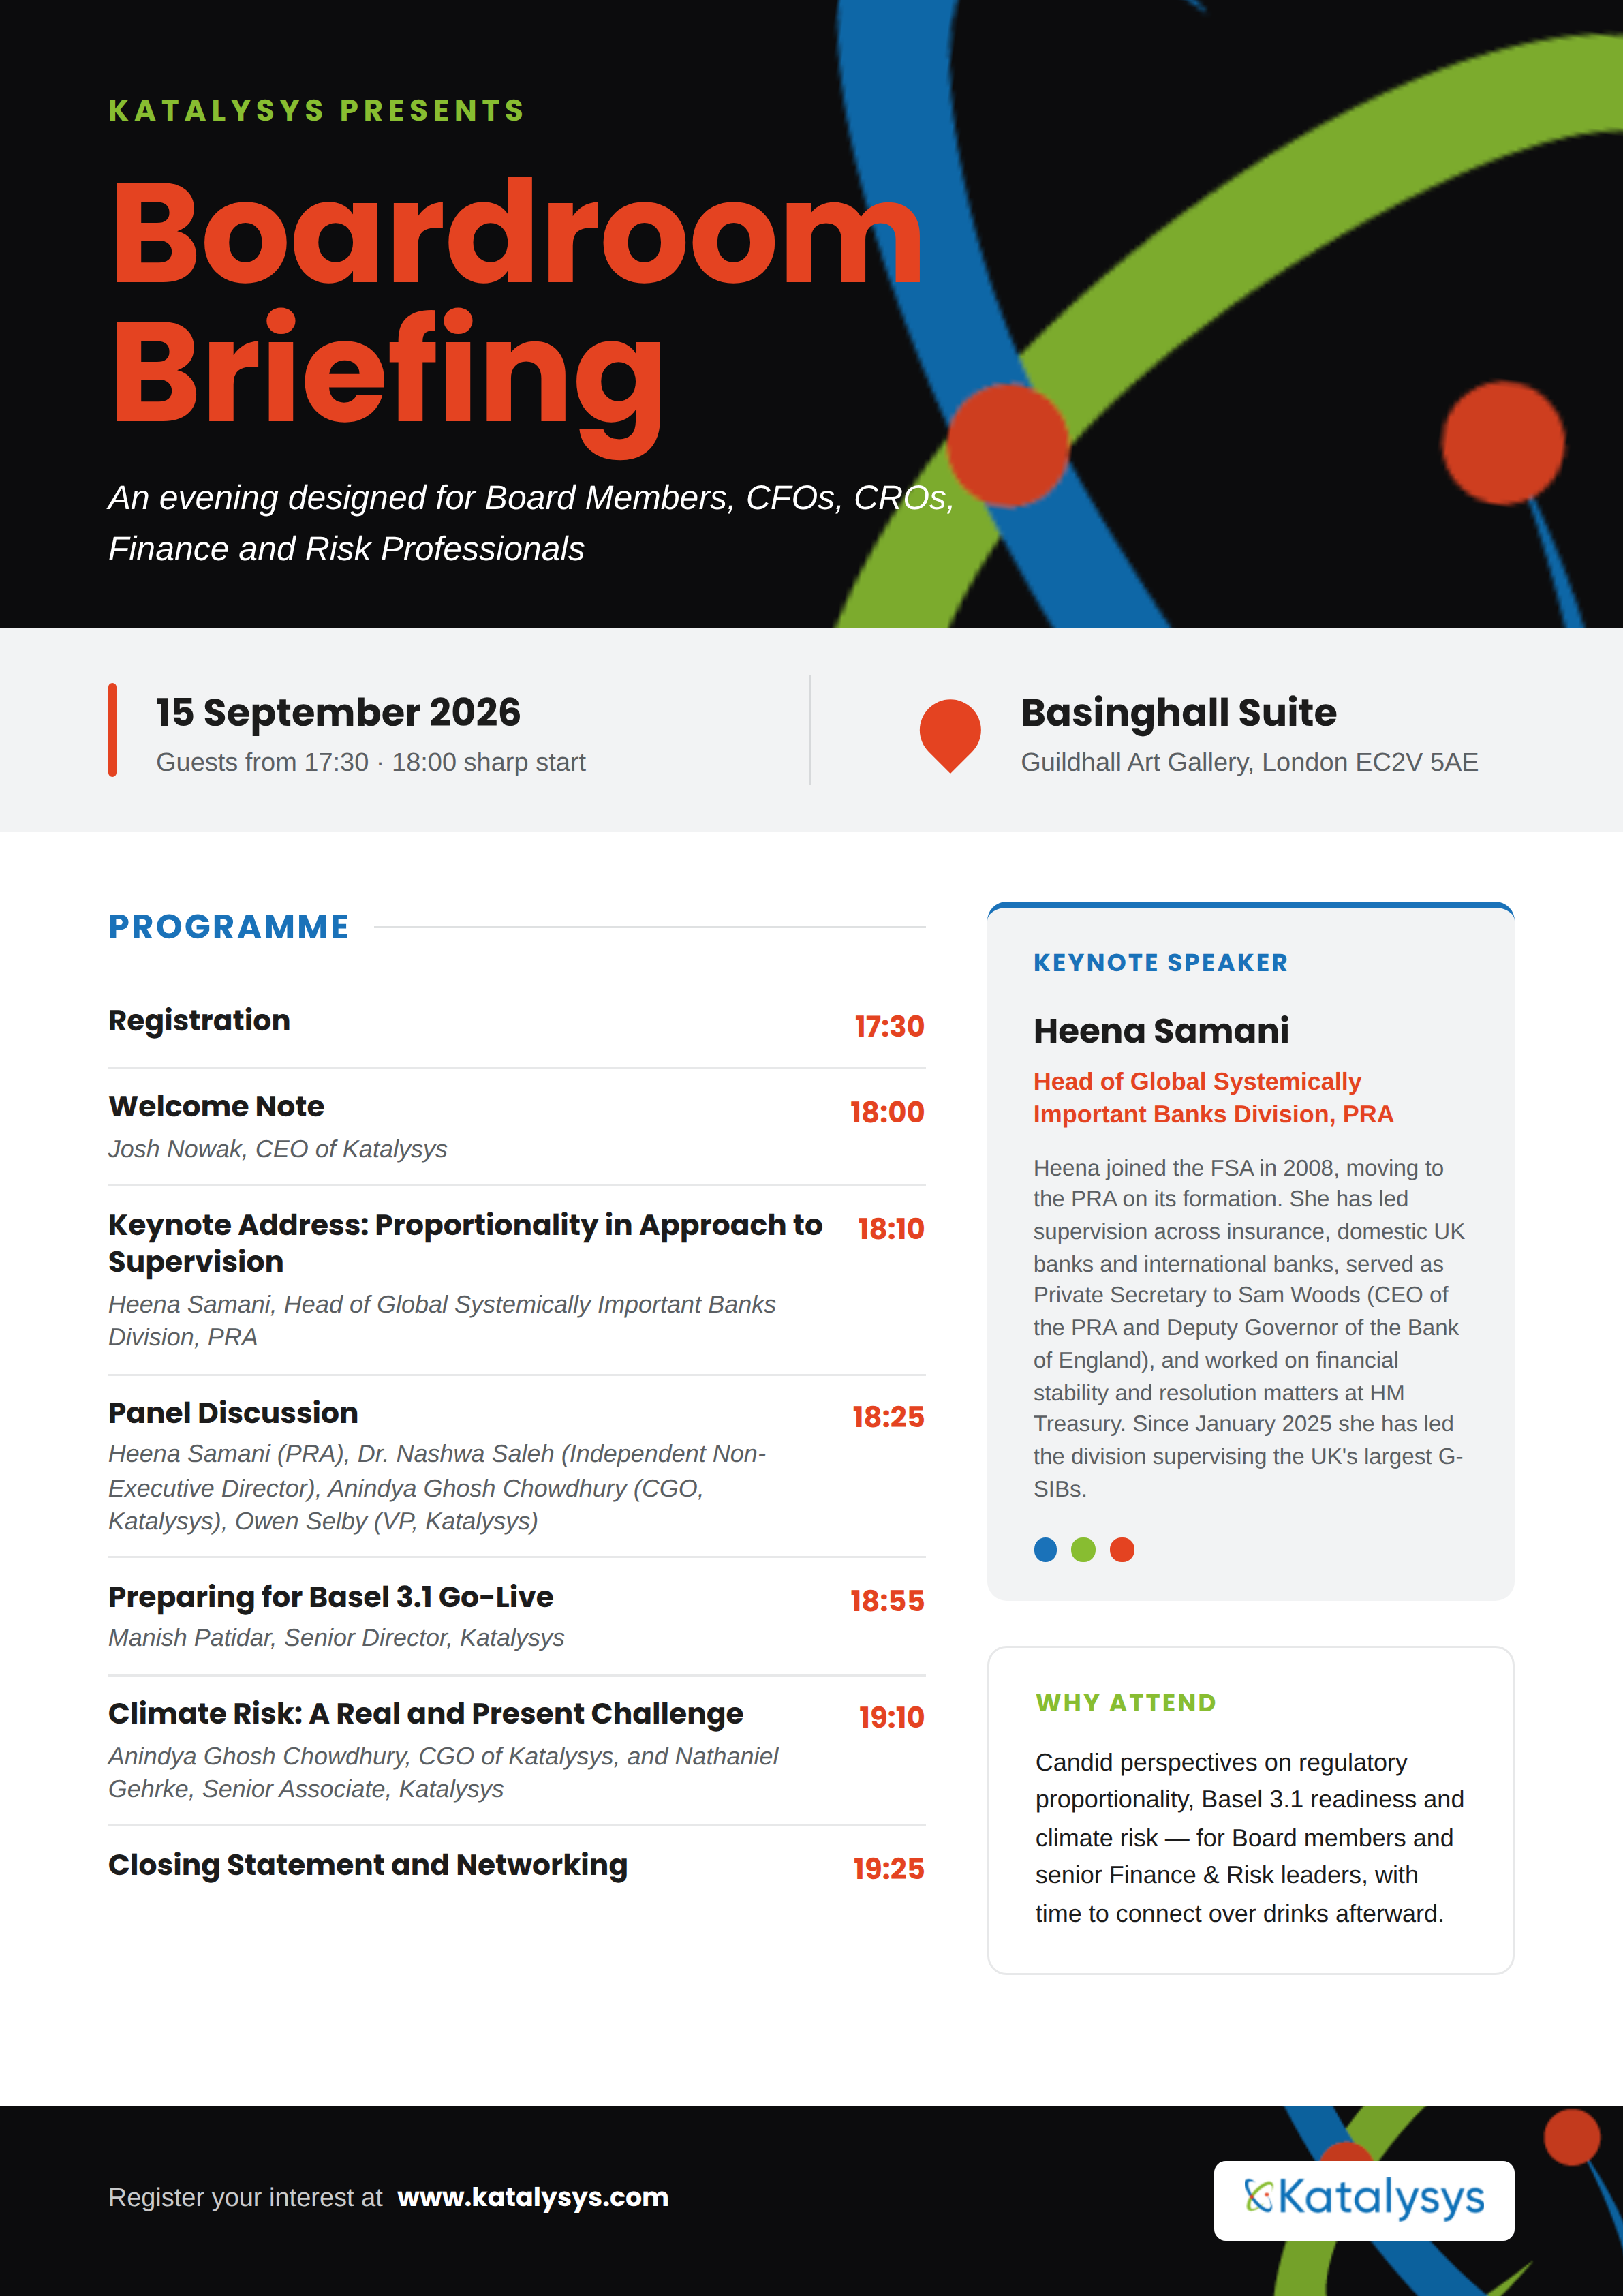
Katalysys is hosting a Boardroom Briefing for Board members, CFOs, CROs, and finance and risk professionals at the Guildhall on 15th of September 2026. Beyond a keynote speech to be delivered by Heena Samani, Head of Global Systemically Important Banks Division in the PRA, our experts will cover preparedness for Basel 3.1, and the rapidly changing picture of climate risks on how banks operate.
CRR2
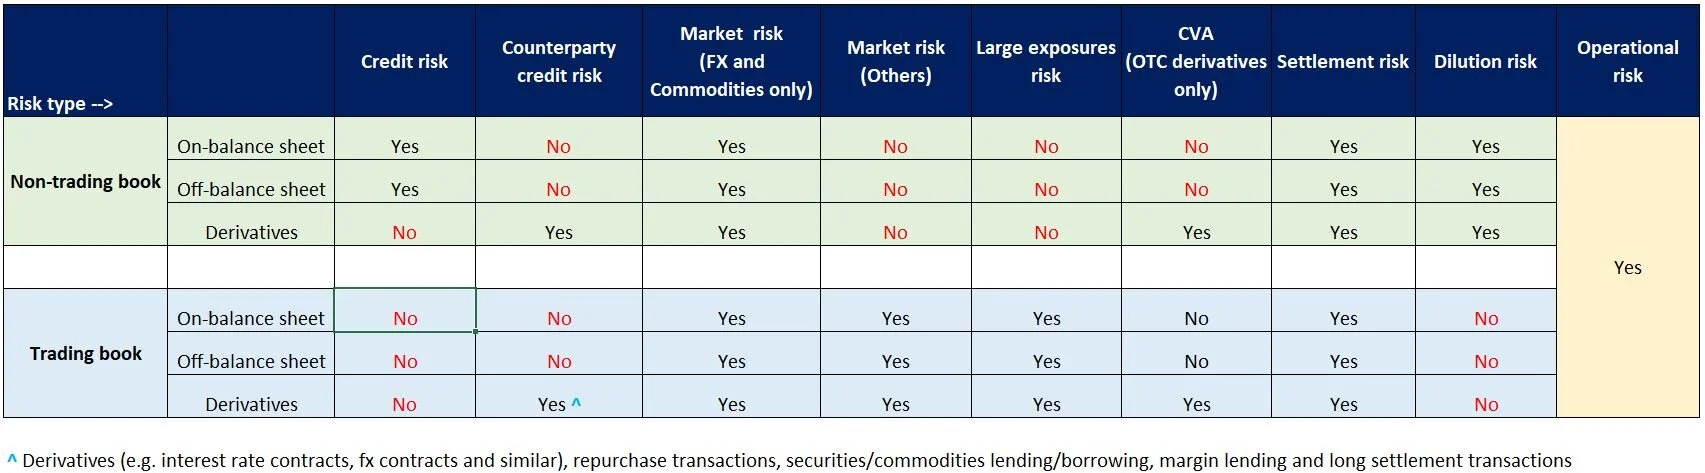
A common question we are asked is the basis on which own funds requirement has to be calculated for the various types of exposures on the non-trading and trading book.
The approach to evaluating risk weight for Collective Investment Undertaking (CIU) exposures has changed under the new CRR2 rules. There are three approaches outlined, and banks can select the specific approach based on the amount of information available about the underlying exposures of the CIUs.
Prudently valued software assets no longer needs to be deducted from CET-1 capital, but can be risk weighted.
The large exposure limits are set based on the bank’s Tier-1 Capital Only.
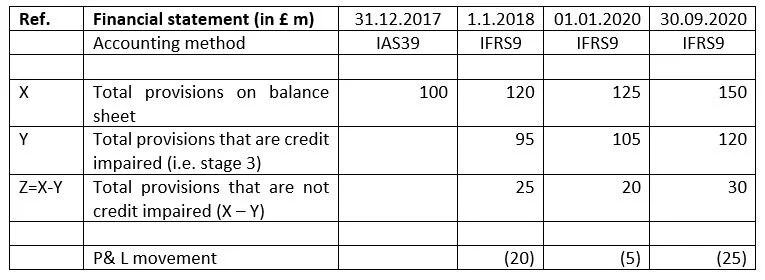
As part of Covid-19 quick fix, the existing IFRS9 transitional arrangement for CET-1 capital adjustment has been extended by 2 years and the additional adjustment for ECL provisions recognised in 2020 and 2021 has also been provided.
SME support factor of 0.7619 for exposures up to €2.5 million and 0.85 for exposures above €2.5 million, for entities with turnover of up to €50 million.
How can we help you?
Katalysys can assist in all aspects of prudential risk management and regulatory reporting requirements caused by the increasing changes to the regulatory environment and the introduction of newer rules. A few of the areas where we have assisted in the past are listed below:-
Identify changes to the bank’s capital and liquidity calculations due to the new rules (e.g. changes to SME support factor introduced in CRR2) and provide guidance as to how the bank can incorporate these in the existing processes and control environment
Advisory and workshops about the new requirement and industry benchmarks
Review of the bank’s existing policies and interpretation in light of the new changes
Analyse the impact on regulatory reporting, and assist in regulatory change management