Overview
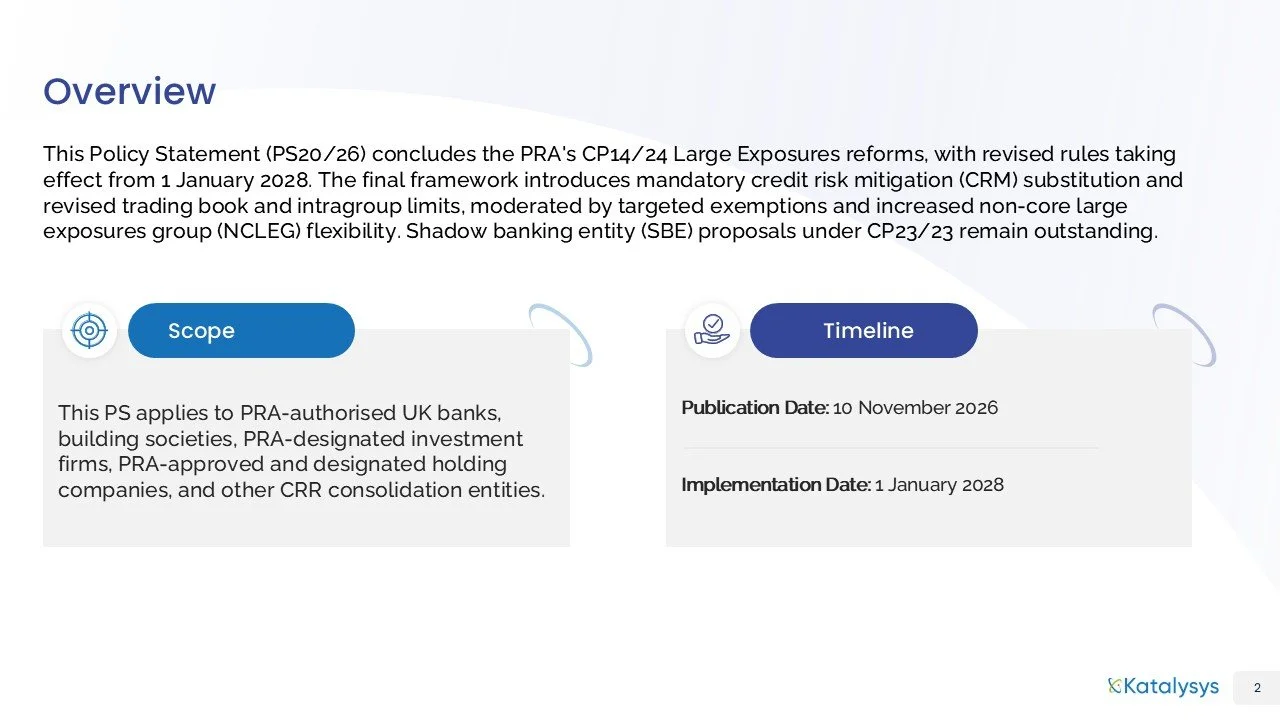
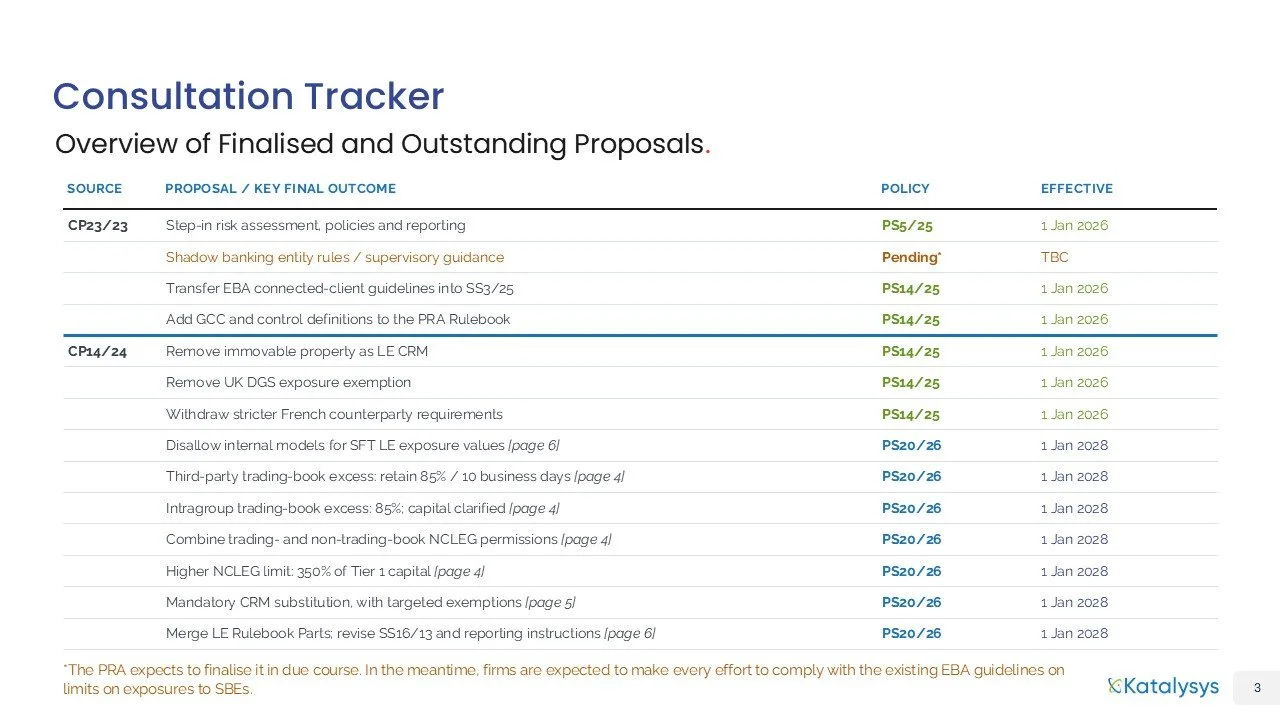
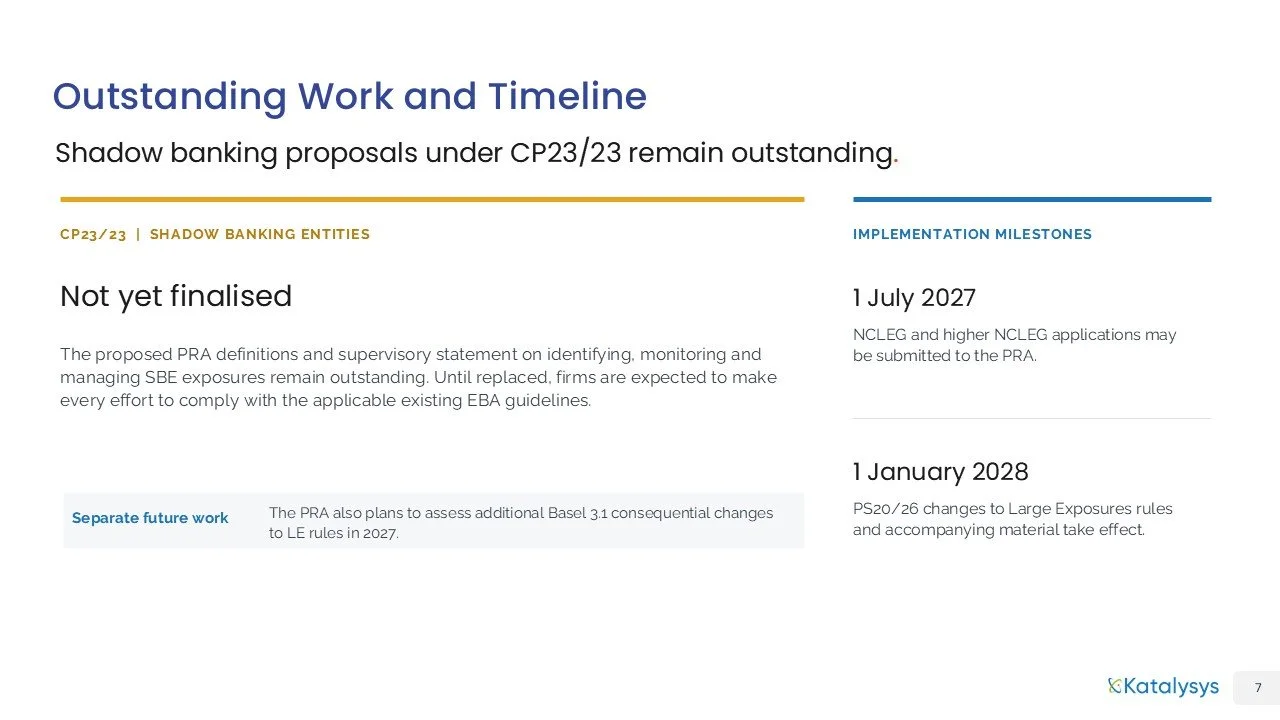
On 10 November 2026, the Prudential Regulation Authority (PRA) published Policy Statement PS20/26, finalising the remaining proposals under CP14/24 relating to the Large Exposures (LE) framework. The revised requirements will take effect from 1 January 2028.
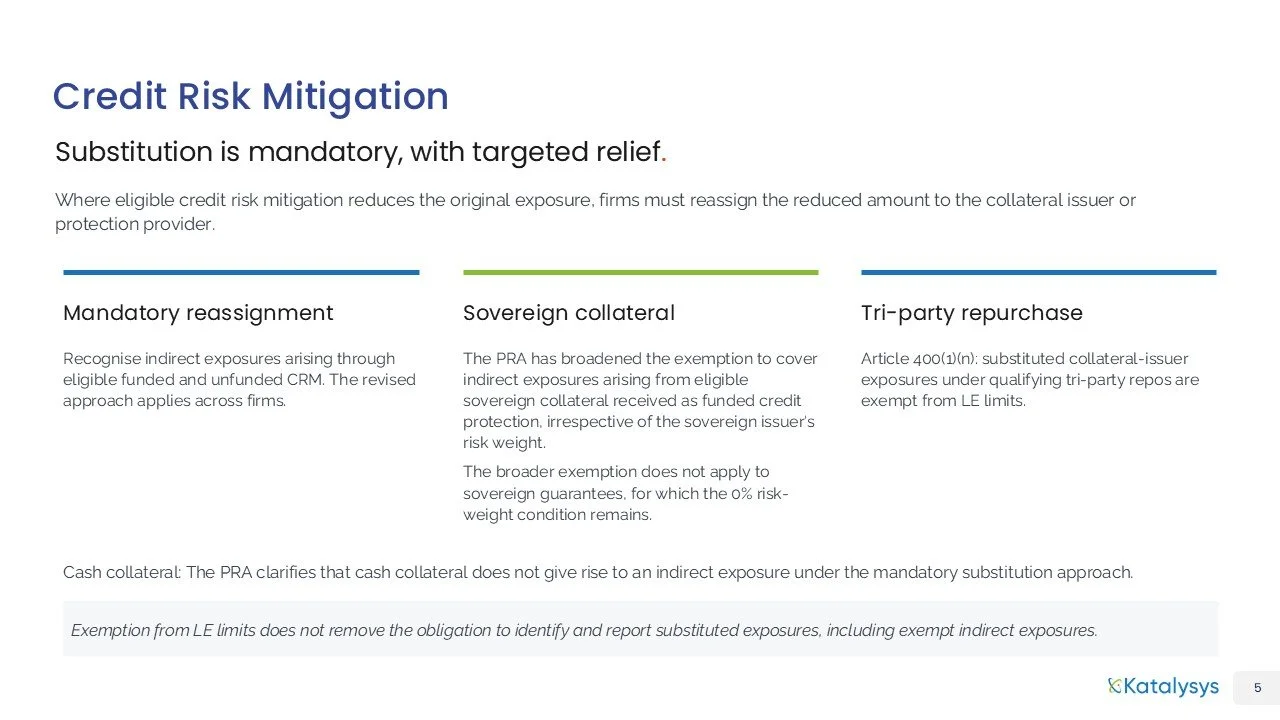
A key change affecting non-systemic UK banks is the introduction of mandatory credit risk mitigation (CRM) substitution. Where eligible collateral or guarantees are recognised to reduce an exposure, firms must recognise the corresponding indirect exposure to the collateral issuer or protection provider for LE purposes.
Following industry feedback, the PRA has introduced targeted exemptions, including for eligible sovereign collateral and qualifying tri-party repurchase agreements. However, firms must continue to identify and report substituted exposures, including those exempt from LE limits.
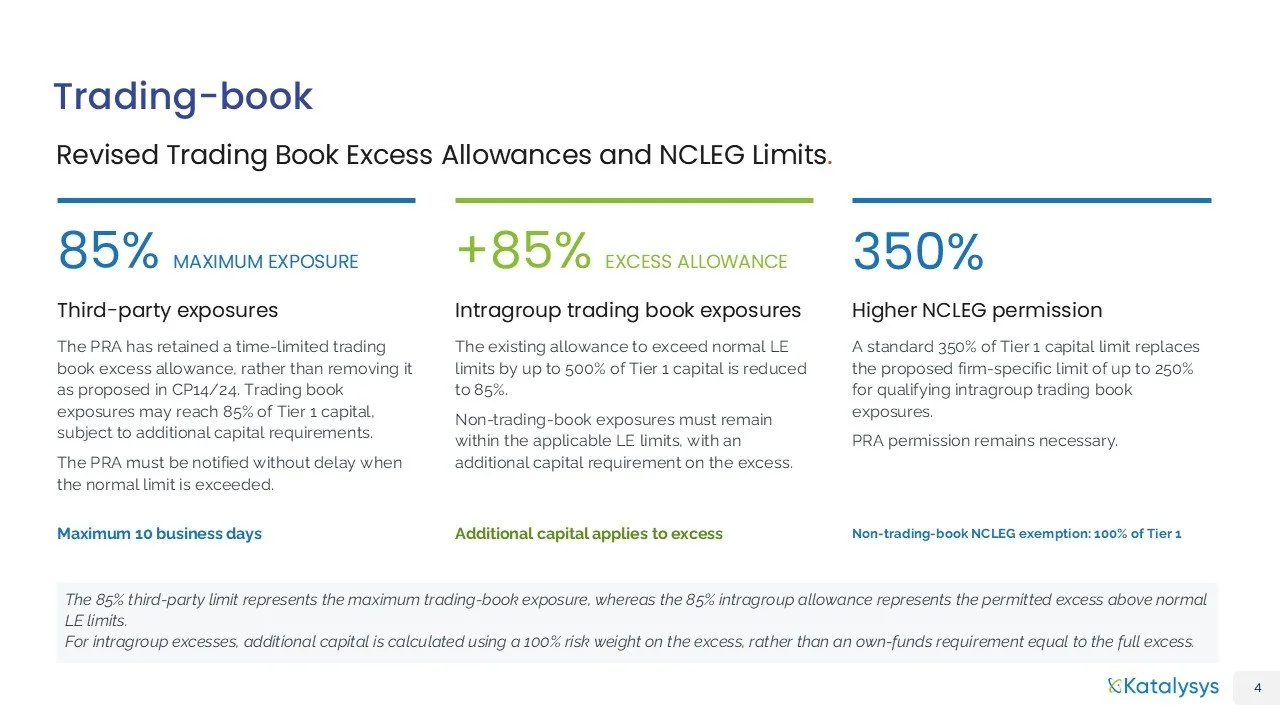
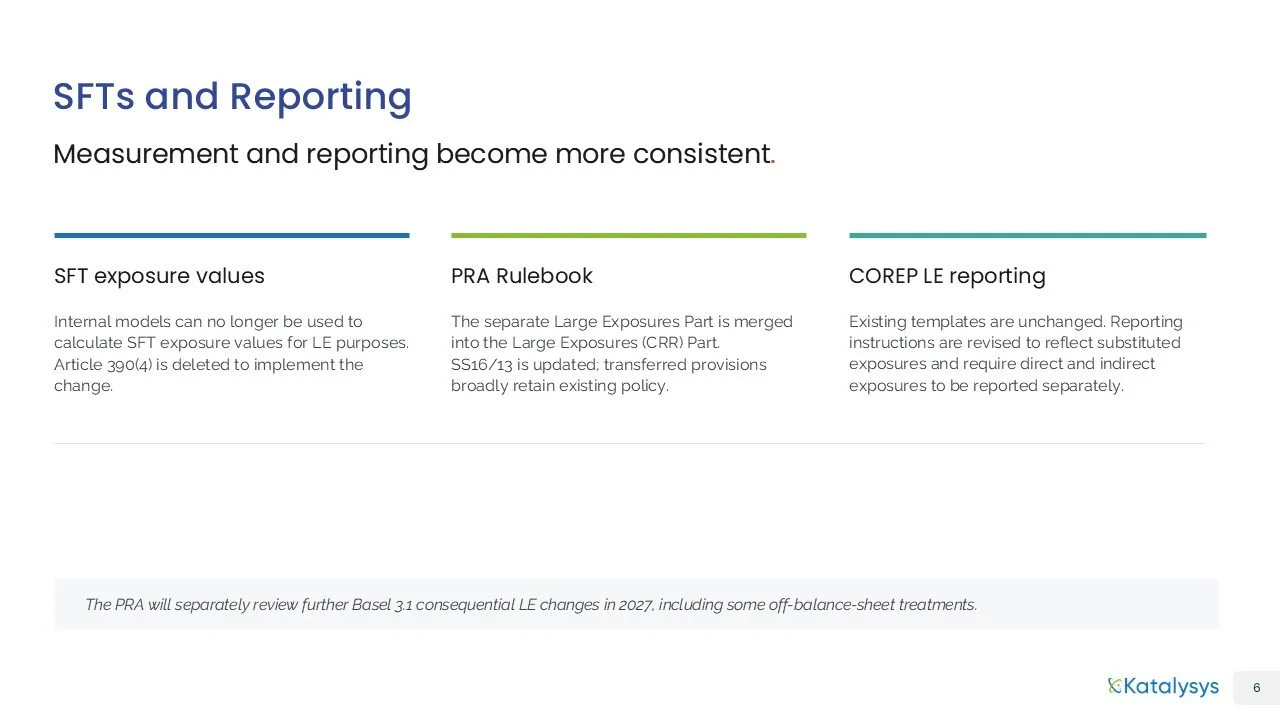
Other changes include revised trading-book excess allowances, increased non-core large exposures group (NCLEG) limits, changes to the calculation of securities financing transaction (SFT) exposures, and updated regulatory reporting instructions.
PS20/26 concludes the PRA's reforms under CP14/24, while the shadow banking entity proposals under CP23/23 remain outstanding.
Further details on the key changes and implementation timelines are provided in our presentation below.